Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
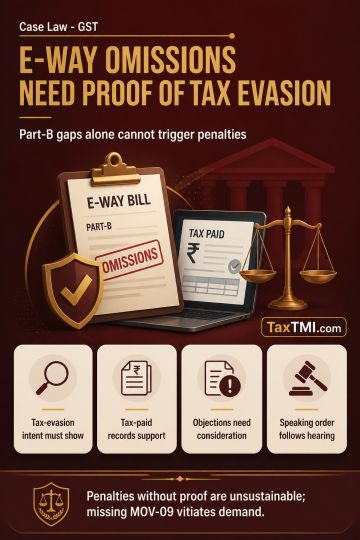
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913