SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Page of 4910
Press 'Enter' after typing page number.
761 to 780 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
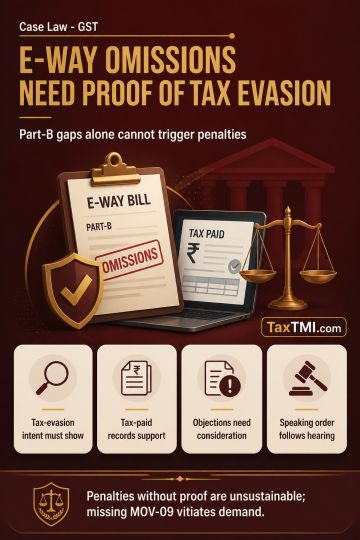
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910