Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
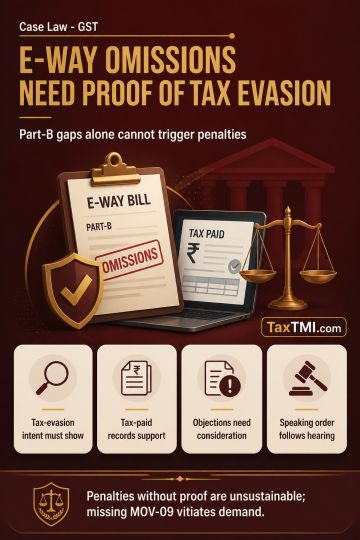
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921