Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Page of 4910
Press 'Enter' after typing page number.
21 to 40 of 98196 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
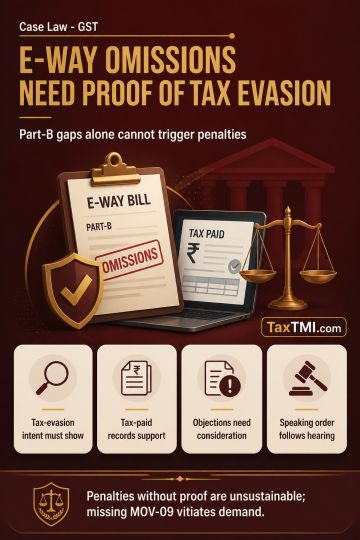
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Section 129 penalties for an unfilled Part-B of an e-way bill require independent, recorded evidence of intent to evade tax; a technical or clerical omission alone is insufficient where invoices, Part-A particulars and other documentation establish a transparent, tax-paid transaction. Penalties imposed without positive proof of tax-evasion intent are legally unsustainable. Following detention and consideration of objections, a final reasoned order in Form GST MOV-09 must be issued after providing a hearing. Failure to issue that speaking order prejudices the taxpayer's rights and vitiates the resulting penalty demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910