Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
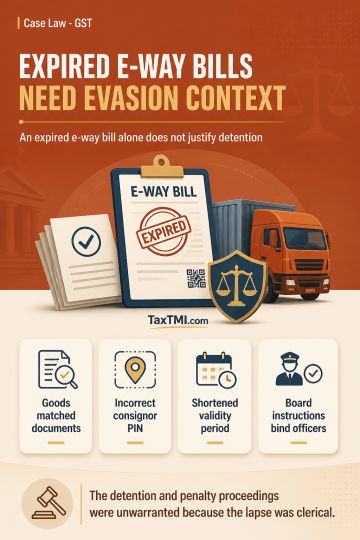
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Section 129 penalty for an expired e-way bill must serve its tax-evasion prevention purpose, notwithstanding that the provision does not expressly require mens rea. Board instructions identifying situations in which section 129 need not be invoked bind the proper officer. Where goods matched the e-way bill and delivery challan, and an erroneous consignor PIN code shortened rather than extended validity, the lapse was clerical. Without any allegation of intent to evade tax, detention and penalty proceedings under section 129 were unwarranted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913