Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Page of 4908
Press 'Enter' after typing page number.
21 to 40 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
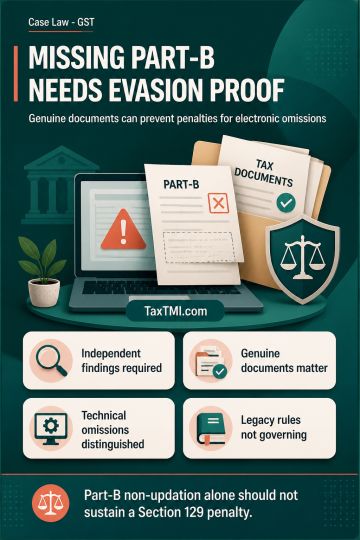
Section 129 penalties for failure to update Part-B of an e-way bill require independent findings of an intent to evade tax where the goods movement is otherwise supported by genuine tax documents. The integrated electronic GST framework distinguishes technical or procedural omissions from active tax-evasion attempts. Where the invoice, Part-A details and underlying transaction transparently establish the movement, non-updation of Part-B alone should not sustain a penalty. Strict-liability principles developed under the legacy manual check-post regime are not treated as governing such electronic GST compliance failures.
Section 129 penalties for failure to update Part-B of an e-way bill require independent findings of an intent to evade tax where the goods movement is otherwise supported by genuine tax documents. The integrated electronic GST framework distinguishes technical or procedural omissions from active tax-evasion attempts. Where the invoice, Part-A details and underlying transaction transparently establish the movement, non-updation of Part-B alone should not sustain a penalty. Strict-liability principles developed under the legacy manual check-post regime are not treated as governing such electronic GST compliance failures.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908