Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
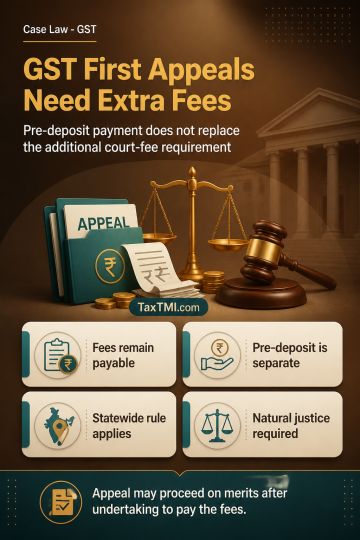
Additional court fees are payable on GST first appeals before the State appellate authority under the applicable court-fees law, notwithstanding the statutory pre-deposit prescribed for filing the appeal. The levy binds both the appellate authority and taxpayers within the State's jurisdiction. Where the appellant undertakes to pay the requisite fees, dismissal of the first appeal for non-payment may be set aside and the matter remanded for decision on merits after observing natural justice.
Additional court fees are payable on GST first appeals before the State appellate authority under the applicable court-fees law, notwithstanding the statutory pre-deposit prescribed for filing the appeal. The levy binds both the appellate authority and taxpayers within the State's jurisdiction. Where the appellant undertakes to pay the requisite fees, dismissal of the first appeal for non-payment may be set aside and the matter remanded for decision on merits after observing natural justice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908