Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
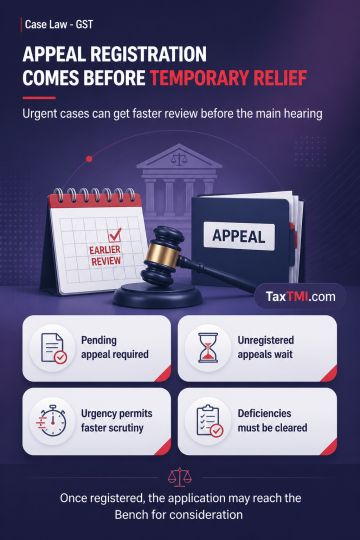
Interlocutory relief under Rule 29 is contemplated only in a pending appeal. Where a statutory appeal remains under scrutiny and is not registered, stay or early-hearing relief cannot receive substantive consideration. Urgency may instead justify expedited scrutiny, subject to procedural compliance. Once deficiencies are cleared and the appeal is registered, the interlocutory application may be tagged to it and placed before the Bench for consideration.
Interlocutory relief under Rule 29 is contemplated only in a pending appeal. Where a statutory appeal remains under scrutiny and is not registered, stay or early-hearing relief cannot receive substantive consideration. Urgency may instead justify expedited scrutiny, subject to procedural compliance. Once deficiencies are cleared and the appeal is registered, the interlocutory application may be tagged to it and placed before the Bench for consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916