Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
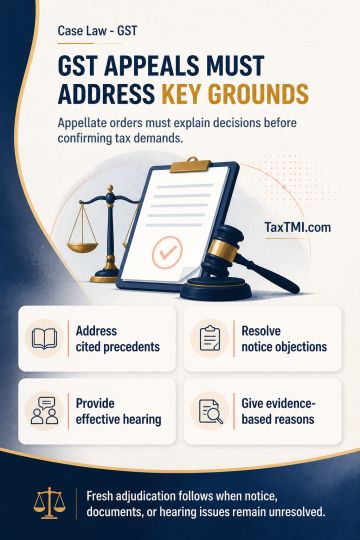
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913