SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Page of 4908
Press 'Enter' after typing page number.
701 to 720 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
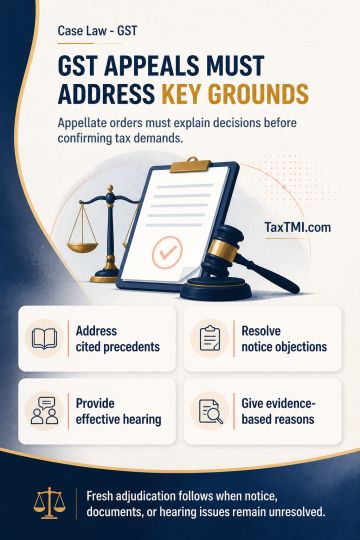
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908