Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
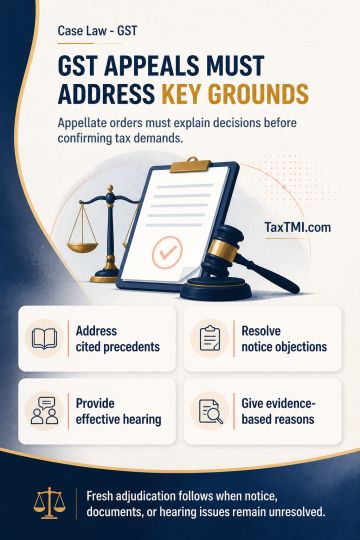
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910