Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
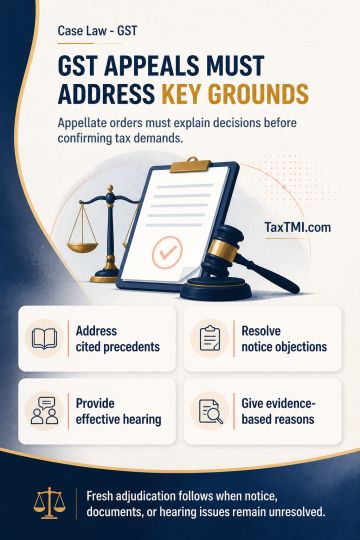
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912