Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
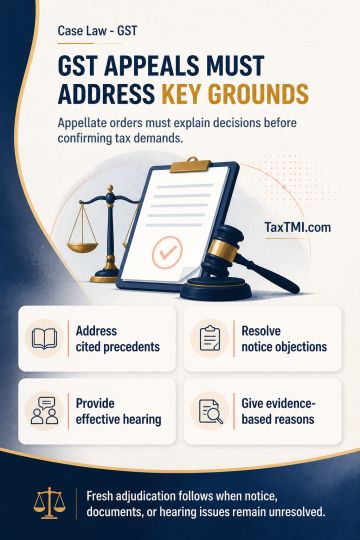
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Reasoned and speaking appellate GST orders must address material grounds of appeal and cited precedents; merely confirming an ex parte demand for lack of satisfactory evidence fails to exercise appellate jurisdiction. Where original adjudication occurred ex parte and objections concerning notice, relied-upon documents, and hearing remain unresolved, remand for fresh original adjudication preserves the appellate remedy. Fresh proceedings require identification and access to relied-upon documents, a reasonable opportunity to respond, an effective personal hearing, and reasoned findings based on evidence. Non-participation without sufficient cause permits determination on the existing record, but not without reasons.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913