Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
Form 26AS evidence requires successor-entity accounting verification after business transfer, while invoice-supported related-party advertising expend...
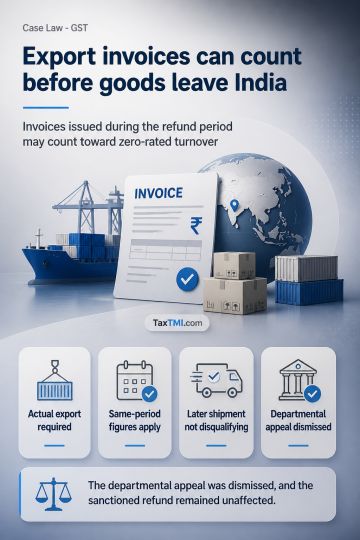
For export refunds under rule 89(4), net input tax credit, turnover of zero-rated supply and adjusted total turnover must correspond to the same relevant period. Export invoices for goods intended for export are issued before or at removal of goods; their value is included in zero-rated turnover where issued during that period, even if the goods are exported later, provided actual export is established. Refund cannot be denied solely because export occurred after the relevant period. An objection that certain input tax credit was inadmissible did not affect the sanctioned refund because the maximum computable refund remained higher than the amount claimed. The departmental appeal was dismissed.
For export refunds under rule 89(4), net input tax credit, turnover of zero-rated supply and adjusted total turnover must correspond to the same relevant period. Export invoices for goods intended for export are issued before or at removal of goods; their value is included in zero-rated turnover where issued during that period, even if the goods are exported later, provided actual export is established. Refund cannot be denied solely because export occurred after the relevant period. An objection that certain input tax credit was inadmissible did not affect the sanctioned refund because the maximum computable refund remained higher than the amount claimed. The departmental appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4923