Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
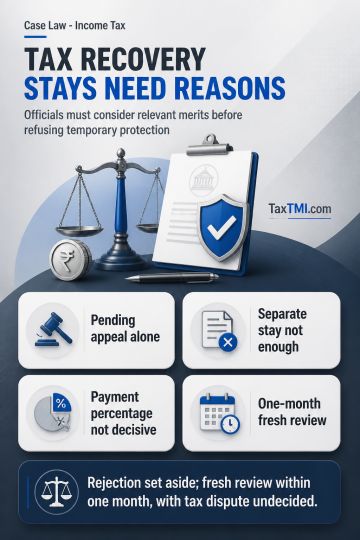
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916