Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Page of 4915
Press 'Enter' after typing page number.
881 to 900 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
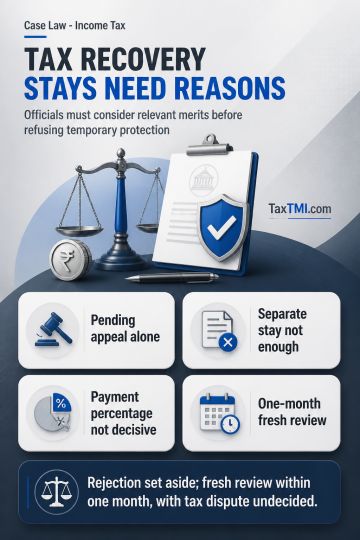
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915