Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
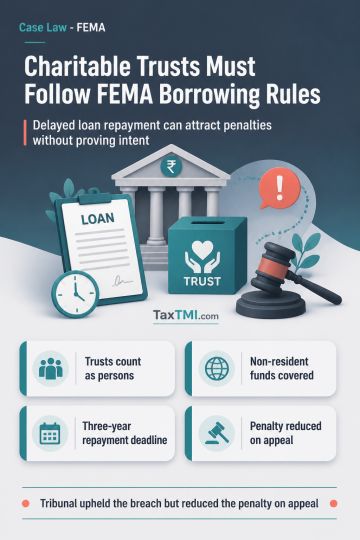
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
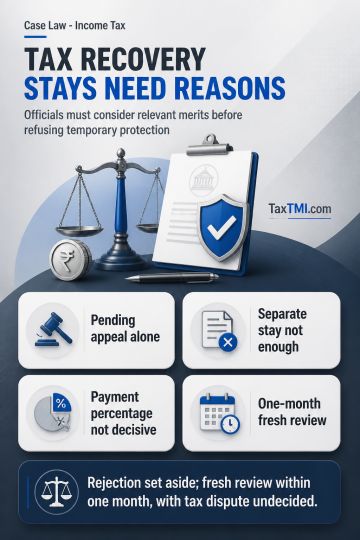
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Stay applications against recovery of disputed income-tax demand require a reasoned exercise of discretion based on factors relevant to granting or refusing interim protection. Rejection solely because an appeal is pending, no separate stay order exists, or the prescribed demand percentage has not been paid under an applicable circular is mechanical and insufficient. The decision-maker must record consideration of the merits relevant to the stay request. The rejection was set aside and remitted to the competent authority for fresh reasoned consideration within one month, without deciding the underlying tax dispute.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912