Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
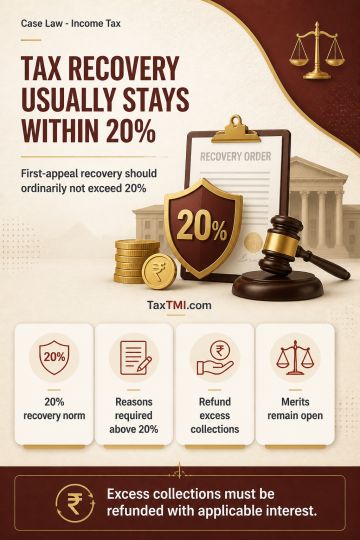
CBDT instructions treat recovery of 20% of disputed tax demand as the ordinary condition for stay pending a first appeal. Recovery above that level requires recorded reasons, including lack of prima facie sustainability of the taxpayer's case or exceptional circumstances. Where a stay order does not record reasons for exceeding the norm, retaining excess collections or adjusting refunds while the stay continues defeats the protection of the stay. Aggregate recoveries and refund adjustments must be verified, and amounts exceeding 20% must be refunded with applicable interest. The assessment and appellate merits remain open.
CBDT instructions treat recovery of 20% of disputed tax demand as the ordinary condition for stay pending a first appeal. Recovery above that level requires recorded reasons, including lack of prima facie sustainability of the taxpayer's case or exceptional circumstances. Where a stay order does not record reasons for exceeding the norm, retaining excess collections or adjusting refunds while the stay continues defeats the protection of the stay. Aggregate recoveries and refund adjustments must be verified, and amounts exceeding 20% must be refunded with applicable interest. The assessment and appellate merits remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918