Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
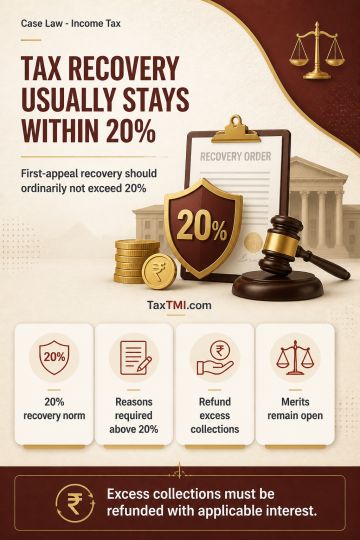
CBDT instructions treat recovery of 20% of disputed tax demand as the ordinary condition for stay pending a first appeal. Recovery above that level requires recorded reasons, including lack of prima facie sustainability of the taxpayer's case or exceptional circumstances. Where a stay order does not record reasons for exceeding the norm, retaining excess collections or adjusting refunds while the stay continues defeats the protection of the stay. Aggregate recoveries and refund adjustments must be verified, and amounts exceeding 20% must be refunded with applicable interest. The assessment and appellate merits remain open.
CBDT instructions treat recovery of 20% of disputed tax demand as the ordinary condition for stay pending a first appeal. Recovery above that level requires recorded reasons, including lack of prima facie sustainability of the taxpayer's case or exceptional circumstances. Where a stay order does not record reasons for exceeding the norm, retaining excess collections or adjusting refunds while the stay continues defeats the protection of the stay. Aggregate recoveries and refund adjustments must be verified, and amounts exceeding 20% must be refunded with applicable interest. The assessment and appellate merits remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915