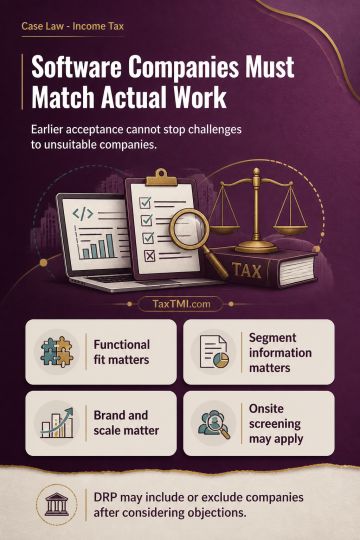
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
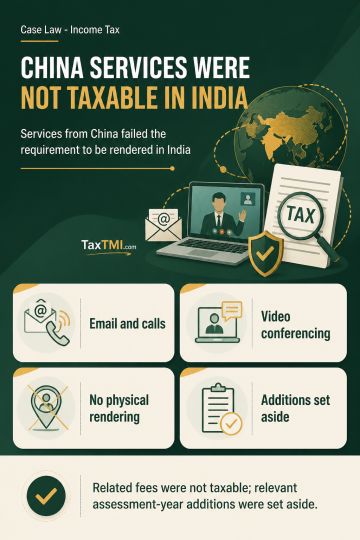
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
Limitation governing correction of TDS statements does not justify an employer's failure to file an original TDS statement or return; where no original filing exists, the correction-time-limit plea is inapplicable. An employer that deducts TDS acts as an agent for its collection and remittance and becomes an assessee in default if it neither deposits deducted tax nor files required returns. Recovery mechanisms, including a charge on the employer's assets, apply against the defaulting employer, while the employee must not suffer for that default. Filed statements require verification and employee grievances require redress.
Limitation governing correction of TDS statements does not justify an employer's failure to file an original TDS statement or return; where no original filing exists, the correction-time-limit plea is inapplicable. An employer that deducts TDS acts as an agent for its collection and remittance and becomes an assessee in default if it neither deposits deducted tax nor files required returns. Recovery mechanisms, including a charge on the employer's assets, apply against the defaulting employer, while the employee must not suffer for that default. Filed statements require verification and employee grievances require redress.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918