Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
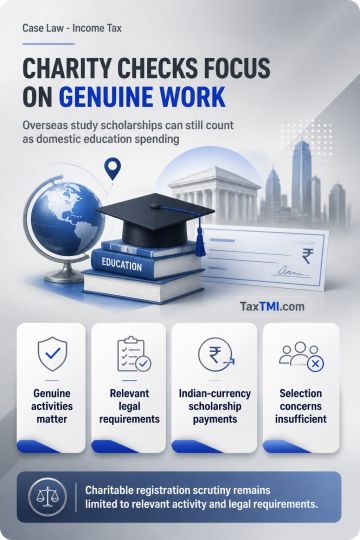
Registration scrutiny of charitable institutions under section 12AB is confined to the genuineness of activities and legal requirements relevant to their objects, rather than assessment-stage examination of income utilisation or payments to specified persons. Scholarships remitted in India in Indian currency to Indian students for overseas higher education constitute domestic application of income, not application outside India merely because studies occur abroad. Such scholarships remain within educational objects where no contrary material establishes otherwise. Concerns regarding scholarship-selection criteria alone do not displace this registration analysis.
Registration scrutiny of charitable institutions under section 12AB is confined to the genuineness of activities and legal requirements relevant to their objects, rather than assessment-stage examination of income utilisation or payments to specified persons. Scholarships remitted in India in Indian currency to Indian students for overseas higher education constitute domestic application of income, not application outside India merely because studies occur abroad. Such scholarships remain within educational objects where no contrary material establishes otherwise. Concerns regarding scholarship-selection criteria alone do not displace this registration analysis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913