Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
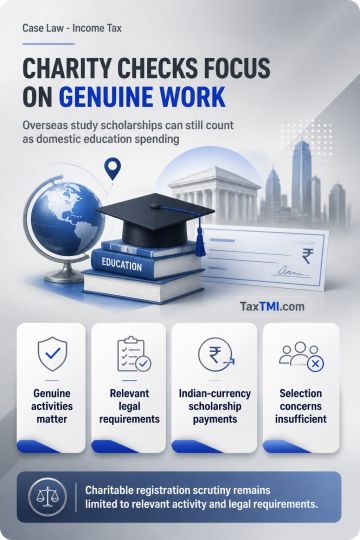
Registration scrutiny of charitable institutions under section 12AB is confined to the genuineness of activities and legal requirements relevant to their objects, rather than assessment-stage examination of income utilisation or payments to specified persons. Scholarships remitted in India in Indian currency to Indian students for overseas higher education constitute domestic application of income, not application outside India merely because studies occur abroad. Such scholarships remain within educational objects where no contrary material establishes otherwise. Concerns regarding scholarship-selection criteria alone do not displace this registration analysis.
Registration scrutiny of charitable institutions under section 12AB is confined to the genuineness of activities and legal requirements relevant to their objects, rather than assessment-stage examination of income utilisation or payments to specified persons. Scholarships remitted in India in Indian currency to Indian students for overseas higher education constitute domestic application of income, not application outside India merely because studies occur abroad. Such scholarships remain within educational objects where no contrary material establishes otherwise. Concerns regarding scholarship-selection criteria alone do not displace this registration analysis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915