Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
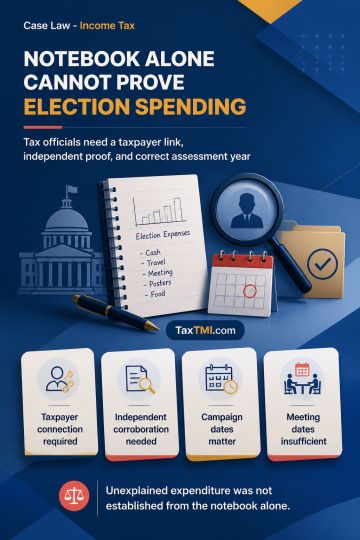
Unexplained election expenditure based on a seized notebook requires proof that the document belongs to or is linked with the taxpayer and independent corroboration of its entries. A notebook recovered from separate commission-agent business premises, without the taxpayer's name, verification from named persons, or other correlation, does not by itself establish unexplained expenditure despite the statutory presumption for seized documents. Undated alleged campaign payments must be assessed in the year supported by campaign, polling, search, and entry-related facts; meeting-schedule dates do not establish the year of payment.
Unexplained election expenditure based on a seized notebook requires proof that the document belongs to or is linked with the taxpayer and independent corroboration of its entries. A notebook recovered from separate commission-agent business premises, without the taxpayer's name, verification from named persons, or other correlation, does not by itself establish unexplained expenditure despite the statutory presumption for seized documents. Undated alleged campaign payments must be assessed in the year supported by campaign, polling, search, and entry-related facts; meeting-schedule dates do not establish the year of payment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916