Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
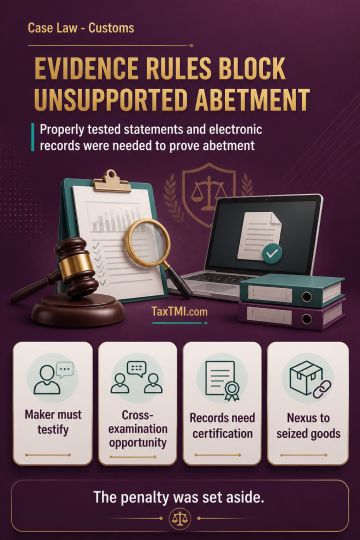
Section 108 statements may be relied on in customs penalty adjudication only after the maker is examined, admissibility is determined in the interests of justice, and the affected person receives an opportunity for cross-examination under Section 138B. Non-compliance renders such statements inadmissible and cannot sustain a penalty founded solely on them. Uncertified call-detail records and WhatsApp chats, particularly where no relevant communications are shown, do not reliably establish collusion. Abetment of gold smuggling requires a nexus to the seized goods or prohibited dealings; a customs employee's omission or negligence alone is insufficient. The penalty was set aside.
Section 108 statements may be relied on in customs penalty adjudication only after the maker is examined, admissibility is determined in the interests of justice, and the affected person receives an opportunity for cross-examination under Section 138B. Non-compliance renders such statements inadmissible and cannot sustain a penalty founded solely on them. Uncertified call-detail records and WhatsApp chats, particularly where no relevant communications are shown, do not reliably establish collusion. Abetment of gold smuggling requires a nexus to the seized goods or prohibited dealings; a customs employee's omission or negligence alone is insufficient. The penalty was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918