Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Source-based taxation of technical service fees requires withholding despite third-party foreign grant payments discharging contractual liability.
    Independent penalty proceedings bar assessment revision solely for non-initiation of under-reporting penalties in completed assessments.
    Personal-use motor cars are personal effects, so their sale cannot generate an allowable long-term capital loss.
    Online gaming withholding applies only to qualifying game winnings, protecting promotional bonuses and unsupported prize-payment disallowances.
    Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
    National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
    Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
    Affixture service of reassessment notices fails without due diligence, correct address verification, and local witness confirmation.
    Immediate preventive suspension requires prompt action; unexplained departmental delay invalidates Customs Broker licence suspension orders.
    Sentencing for customs misdeclaration of red sander exports follows the lower penalty where Section 123 coverage remains unproved.
    Special Advance Authorisation imports retain duty exemption despite Minimum Import Price conditions for polyester knitted fabric imports.
    Prospective customs notification amendments cannot block provisional release of specialised second-hand equipment shipped under earlier Bills of Ladin...
    Anti-dumping duty on castings does not extend to imported wind-turbine gear boxes as complete components.
    Written Acceptance of Customs Reassessment Does Not Bar Challenges to Unsupported Valuation Enhancements under Statutory Valuation Safeguards
    Specific tariff classification for LCD panels overrides vehicle-parts treatment, eliminating differential duty, interest, and penalties.
    Embedded communication modules qualify as apparatus parts and may receive basic customs duty exemption outside excluded consumer devices.
    Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
    Fraudulent CIRP initiation permits recall, but a mature collective process may continue after stakeholder assessment.
    Mandatory liquidation after CIRP expiry applies despite failed CoC liquidation vote, later expressions of interest, or MSME eligibility claims.
    Further investigation under anti-money-laundering law may continue before charges are framed without prior Criminal Court permission.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

One-time settlement by a personal guarantor with the sole...

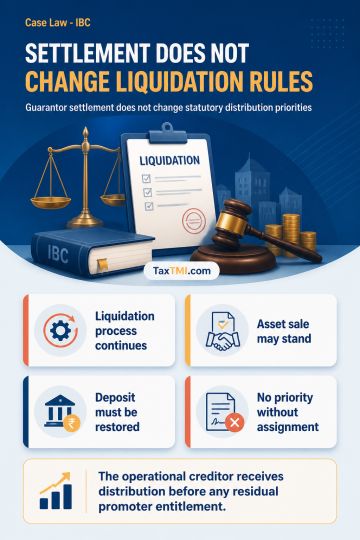
One-time settlement during liquidation does not change statutory distribution, and guarantors gain no creditor priority without debt assignment.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

IBC September 30, 2026 Case Laws AT
One-time settlement by a personal guarantor with the sole financial creditor does not remove a corporate debtor from liquidation or alter the process except through statutory routes. An asset transfer approved after failed auctions may remain undisturbed where the consideration exceeds the reserve price and highest bid, despite procedural non-compliance, because it advances value maximisation. A forfeited earnest money deposit remains part of the liquidation estate and must be restored once the creditor's claim is fully settled. Settlement does not confer financial creditor status on a personal guarantor without assignment or substitution of debt; the admitted operational creditor receives distribution under the statutory waterfall before any residual promoter entitlement. Liquidator remuneration and expenses remain payable from the estate.

Topics

Acts Income Tax