Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
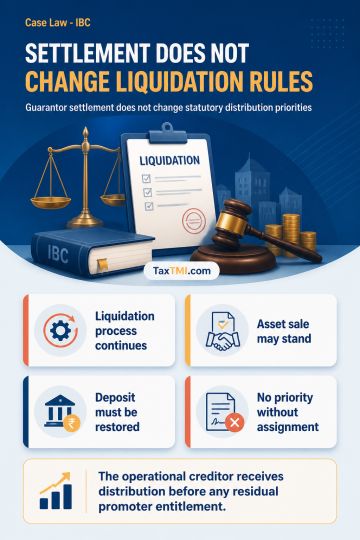
One-time settlement by a personal guarantor with the sole financial creditor does not remove a corporate debtor from liquidation or alter the process except through statutory routes. An asset transfer approved after failed auctions may remain undisturbed where the consideration exceeds the reserve price and highest bid, despite procedural non-compliance, because it advances value maximisation. A forfeited earnest money deposit remains part of the liquidation estate and must be restored once the creditor's claim is fully settled. Settlement does not confer financial creditor status on a personal guarantor without assignment or substitution of debt; the admitted operational creditor receives distribution under the statutory waterfall before any residual promoter entitlement. Liquidator remuneration and expenses remain payable from the estate.
One-time settlement by a personal guarantor with the sole financial creditor does not remove a corporate debtor from liquidation or alter the process except through statutory routes. An asset transfer approved after failed auctions may remain undisturbed where the consideration exceeds the reserve price and highest bid, despite procedural non-compliance, because it advances value maximisation. A forfeited earnest money deposit remains part of the liquidation estate and must be restored once the creditor's claim is fully settled. Settlement does not confer financial creditor status on a personal guarantor without assignment or substitution of debt; the admitted operational creditor receives distribution under the statutory waterfall before any residual promoter entitlement. Liquidator remuneration and expenses remain payable from the estate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915