Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Page of 4908
Press 'Enter' after typing page number.
21 to 40 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
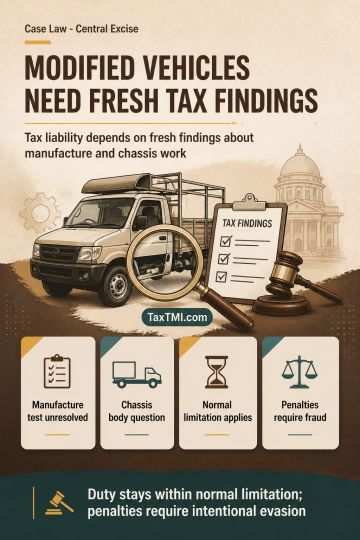
Excise liability for modifications to fully built motor vehicles depends on whether refining or remaking amounts to manufacture and, where a Chapter Note is invoked, whether a body was built on the chassis as received. These foundational questions require fresh determination before excisability and chassis-based exemption can be resolved. Extended limitation requires a positive, deliberate suppression or misstatement intended to evade duty; registration, returns, departmental scrutiny and a bona fide exemption belief do not establish that standard merely because the departmental view later changes. Any duty determined is confined to the normal limitation period. Penalties for the manufacturer and its Executive Director require the same fraud or intentional-evasion conditions and therefore do not arise absent such conduct.
Excise liability for modifications to fully built motor vehicles depends on whether refining or remaking amounts to manufacture and, where a Chapter Note is invoked, whether a body was built on the chassis as received. These foundational questions require fresh determination before excisability and chassis-based exemption can be resolved. Extended limitation requires a positive, deliberate suppression or misstatement intended to evade duty; registration, returns, departmental scrutiny and a bona fide exemption belief do not establish that standard merely because the departmental view later changes. Any duty determined is confined to the normal limitation period. Penalties for the manufacturer and its Executive Director require the same fraud or intentional-evasion conditions and therefore do not arise absent such conduct.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908