Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
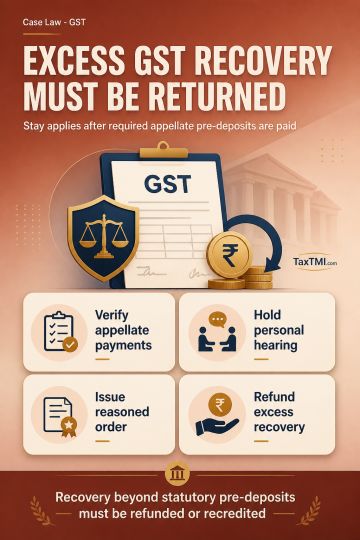
Statutory stay of the balance GST demand applies once the prescribed cumulative appellate pre-deposits are paid under the GST enactment. The High Court did not determine whether the required deposits had actually been made or whether recovery from the Electronic Cash Ledger exceeded those deposits. It directed independent consideration of the taxpayer's representation after a personal hearing and required a reasoned and speaking order within the stipulated period. Any recovery found to exceed the cumulative statutory pre-deposits must be refunded or recredited. The underlying merits of the GST demand remain open.
Statutory stay of the balance GST demand applies once the prescribed cumulative appellate pre-deposits are paid under the GST enactment. The High Court did not determine whether the required deposits had actually been made or whether recovery from the Electronic Cash Ledger exceeded those deposits. It directed independent consideration of the taxpayer's representation after a personal hearing and required a reasoned and speaking order within the stipulated period. Any recovery found to exceed the cumulative statutory pre-deposits must be refunded or recredited. The underlying merits of the GST demand remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915