Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Page of 4915
Press 'Enter' after typing page number.
481 to 500 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
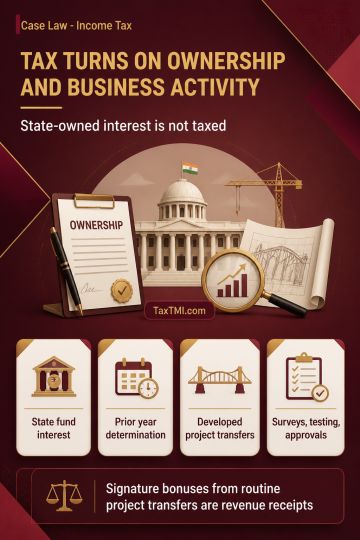
Interest arising from State Government funds advanced to an assessee is not taxable in the assessee's hands where the interest belongs to the State Government, including where the same issue has been determined for an earlier assessment year. Conversely, a signature bonus received on transferring developed power projects constitutes a revenue receipt when developing and transferring such projects forms part of the taxpayer's ordinary business and involves expenditure on surveys, testing and approvals. The distinction turns on beneficial ownership of the interest and the receipt's direct connection with regular business operations.
Interest arising from State Government funds advanced to an assessee is not taxable in the assessee's hands where the interest belongs to the State Government, including where the same issue has been determined for an earlier assessment year. Conversely, a signature bonus received on transferring developed power projects constitutes a revenue receipt when developing and transferring such projects forms part of the taxpayer's ordinary business and involves expenditure on surveys, testing and approvals. The distinction turns on beneficial ownership of the interest and the receipt's direct connection with regular business operations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915