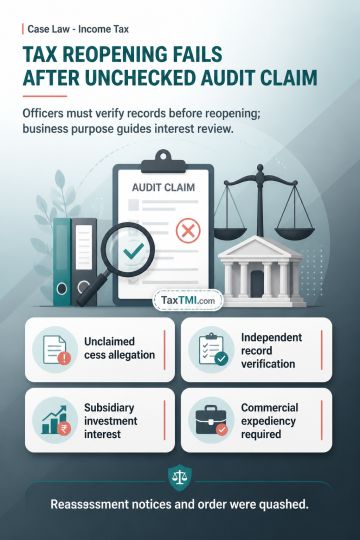
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
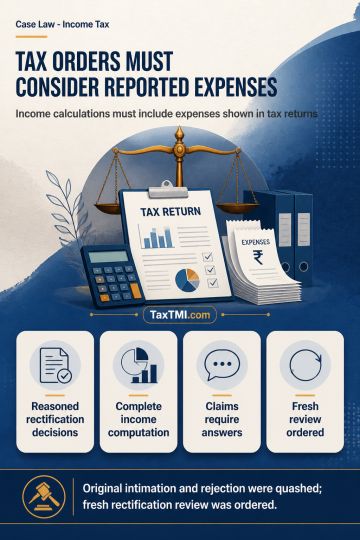
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Third-party loose sheets require reliable nexus before supporting unexplained expenditure additions; presumptions do not establish payer identity or o...
TNMM comparability using audited accounts and working-capital adjustments can eliminate unwarranted transfer-pricing additions where verified margins ...
Gross-profit additions on disputed purchases require reasoned appellate determination; disclosed claims alone do not support inaccurate-particulars pe...
Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Page of 4915
Press 'Enter' after typing page number.
501 to 520 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Writ jurisdiction against a GST adjudication order is generally...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedings.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Writ jurisdiction against a GST adjudication order is generally unavailable where an efficacious statutory appeal was not pursued within time and delay remains unexplained; a pending rectification application does not create a fresh period to challenge the original order. The statutory restriction on parallel GST proceedings applies only where proceedings concern the same subject matter, rather than merely the same assessee, period, transactions, or factual background. Proceedings based on incorrect tax liability and inadmissible input tax credit may continue independently from allegations of fraudulent credit without actual supply. The bar on duplicate penalties requires a prior penalty imposed on the person concerned for the same act or omission.
Writ jurisdiction against a GST adjudication order is generally unavailable where an efficacious statutory appeal was not pursued within time and delay remains unexplained; a pending rectification application does not create a fresh period to challenge the original order. The statutory restriction on parallel GST proceedings applies only where proceedings concern the same subject matter, rather than merely the same assessee, period, transactions, or factual background. Proceedings based on incorrect tax liability and inadmissible input tax credit may continue independently from allegations of fraudulent credit without actual supply. The bar on duplicate penalties requires a prior penalty imposed on the person concerned for the same act or omission.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915