Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
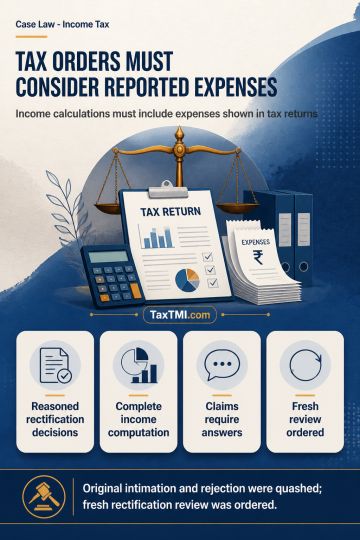
Reasoned rectification orders require consideration of expenditure disclosed in income-tax returns, preventing revision based on incomplete income com...
Modified returns after business reorganisations cannot trigger fresh scrutiny once the original assessment was complete, invalidating related transfer...
Page of 4915
Press 'Enter' after typing page number.
501 to 520 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 93 of the CGST Act permits post-death determination of tax, interest or penalty through a legal representative, without requiring adjudication to have begun during the deceased's lifetime. Liability remains confined to estate assets and does not attribute the underlying contravention to the representative; effective hearing and appellate safeguards support its constitutional validity. Pure questions concerning Section 93 may be examined in writ jurisdiction despite an alternative remedy, but factual and merits disputes, including service, proof, representative-liability conditions and penalty computation, belong in statutory appeal. Retention or appropriation of investigation deposits requires a disclosed lawful basis and reasoned determination after hearing; any unsupported balance must be released with accrued fixed-deposit interest.
Section 93 of the CGST Act permits post-death determination of tax, interest or penalty through a legal representative, without requiring adjudication to have begun during the deceased's lifetime. Liability remains confined to estate assets and does not attribute the underlying contravention to the representative; effective hearing and appellate safeguards support its constitutional validity. Pure questions concerning Section 93 may be examined in writ jurisdiction despite an alternative remedy, but factual and merits disputes, including service, proof, representative-liability conditions and penalty computation, belong in statutory appeal. Retention or appropriation of investigation deposits requires a disclosed lawful basis and reasoned determination after hearing; any unsupported balance must be released with accrued fixed-deposit interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915