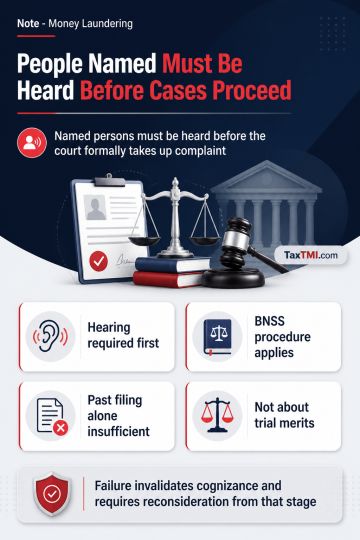
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
Reassessment of a section 80JJAA deduction cannot rest solely on a change of opinion where the deduction was specifically examined and accepted during the original scrutiny assessment. Employee, cost and supporting details had been furnished for the original assessment, while the reopening notice and the order under section 148A(d) identified no fresh tangible material indicating income escapement. The reassessment proceedings were therefore invalidated as a review of material already considered, and the section 148 notice and section 148A(d) order were quashed.
Reassessment of a section 80JJAA deduction cannot rest solely on a change of opinion where the deduction was specifically examined and accepted during the original scrutiny assessment. Employee, cost and supporting details had been furnished for the original assessment, while the reopening notice and the order under section 148A(d) identified no fresh tangible material indicating income escapement. The reassessment proceedings were therefore invalidated as a review of material already considered, and the section 148 notice and section 148A(d) order were quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913