Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certification for tax compliance purposes.
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certificates throughout its effective tax years.
    Scientific research approval requires continuing SIRO status, annual donation reporting, and donor certification for tax-recognised contributions.
    Debenture trustee oversight: consolidated rules mandate independent security diligence, continuous covenant monitoring, default action, and investor g...
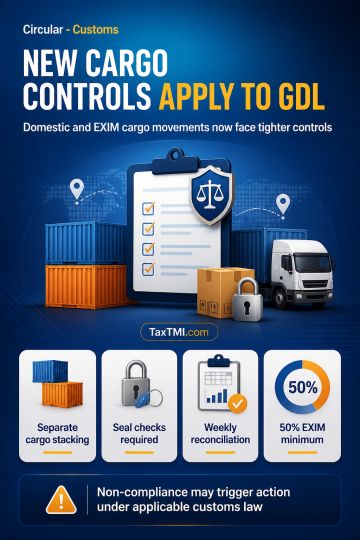
    Customs-controlled cargo movement now includes GDL, subject to EXIM prioritisation, segregation, verification, reconciliation and enforcement safeguar...
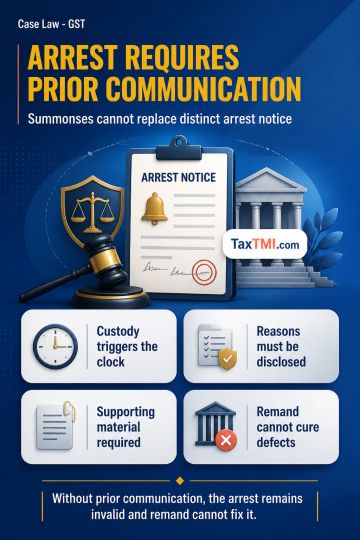
    Prior communication of CGST arrest authorisation is required; summonses cannot replace a distinct pre-arrest notice.
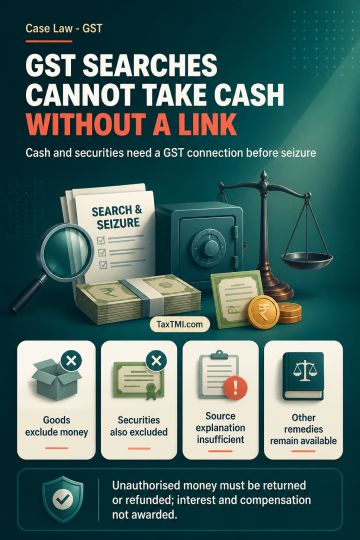
    GST search seizure powers exclude cash and securities absent a statutory nexus, requiring return or refund of unlawfully seized funds.
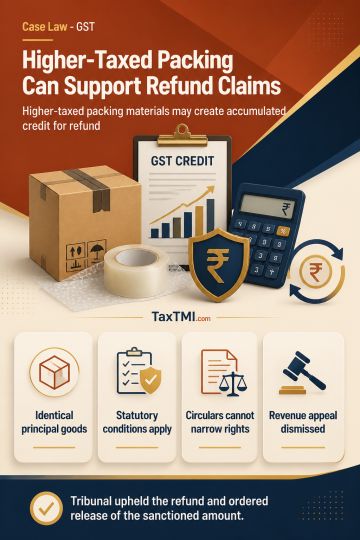
    Inverted duty refunds remain available where higher-taxed packing materials create accumulated ITC, despite restrictive administrative circulars.
    Misdescription of goods in transit records supports section 129 tax and penalty; post-interception documents cannot cure the breach.
    Pre-movement e-way bill compliance makes post-interception documents ineffective, supporting detention and penalty for undocumented goods in transit.
    E-invoice procedural lapse alone cannot sustain detention penalty where transport records establish a genuine taxable supply without tax evasion.
    Tariff classification of oversized kitchen exhaust hoods places integral-fan units in the residual entry rather than fans.
    Defence end-use customs exemption covers missile-warning components, but each import requires prescribed certification and customs verification.
    Fraud-based GST recovery requires show cause notices to state foundational facts, not merely recite statutory grounds.
    GST cross-empowerment remains effective without conditional notification, while duplicate proceedings require established safeguards against overlappi...
    Expiry of seizure period requires release of seized mobile phones and debit cards where no extension order exists.
    Cash seizure under GST search powers was impermissible, requiring interest on refunded cash and release of retained devices.
    Electronic Cash Ledger balances do not discharge GST liabilities until debit, sustaining delayed-payment interest and recovery.
    Doctrine of merger preserves writ review after time-barred GST registration appeal and enables conditional registration restoration.
    Input tax credit requires supplier tax payment; insolvency proceedings do not remove the recipient's statutory condition.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Discounted cash flow valuation of equity shares and compulsorily...

Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure additions.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 28, 2026 Case Laws AT
Discounted cash flow valuation of equity shares and compulsorily convertible preference shares must be assessed as at the valuation date; subsequent actual cash flows, initial operating losses, or absence of positive cash flows do not alone invalidate projections. Substitution of the discounted cash flow method with net asset value valuation was therefore inappropriate, and the share-premium addition was deleted. Vendor-confirmation differences did not justify treating recorded business expenses as unexplained where audited books recorded the transactions, payments passed through banking channels, and business operations funded the expenditure; the unexplained-expenditure addition was deleted. Penalty-initiation challenges were premature because penalty proceedings remain separate from assessment proceedings.

Topics

Acts Income Tax