Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
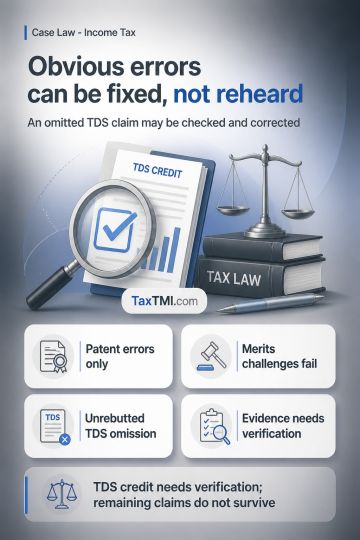
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913