Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
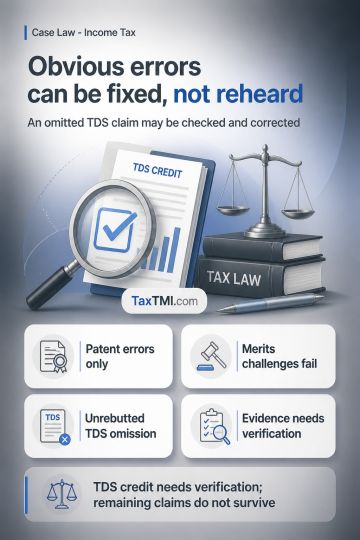
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913