Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
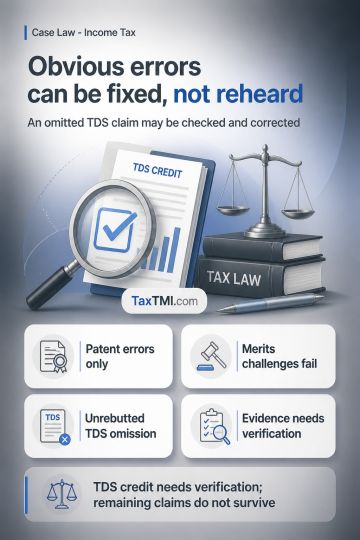
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910