Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
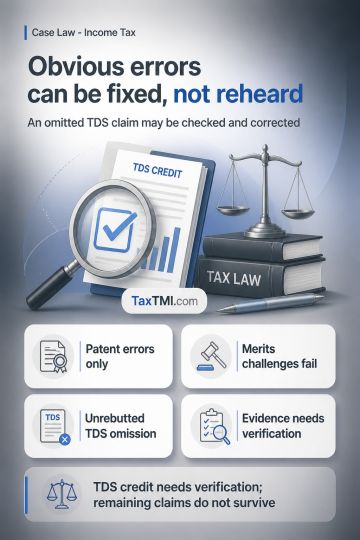
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915