Request-driven road restoration attracts reverse-charge GST, not governmental-function treatment or compensatory-damages status for business recipient...
Road restoration charges for commercial pipeline works are taxable Government services, with reverse charge liability and no public-function exemption...
Model-wise import cap monitoring cannot justify withholding used multifunction machines where all-India tracking is absent and full security is furnis...
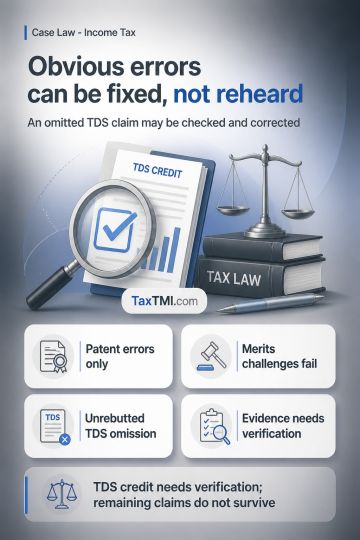
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Rectification for a mistake apparent from the record is limited to patent, manifest and self-evident errors identifiable without prolonged reasoning. Detailed challenges to remand directions on an AMP transfer-pricing adjustment or an associated-enterprise share purchase seek a review on merits and fall outside section 254(2); those rectification requests fail. Omission to decide an unrebutted claim for TDS credit constitutes a rectifiable omission. Supporting evidence requires verification before TDS credit is granted in accordance with law, while the remaining rectification claims do not survive.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912