Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
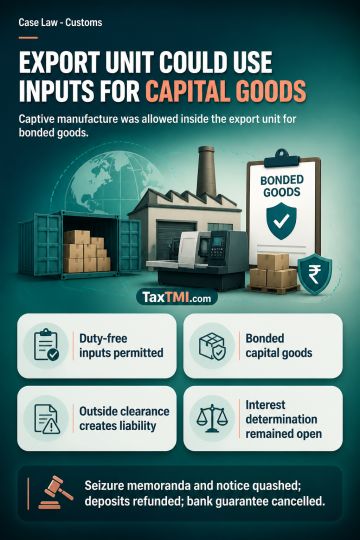
Duty-free inputs common to finished goods and capital goods may be used for captive manufacture within a 100% Export Oriented Unit where capital goods are accounted for and bonded. Liability arises if those capital goods are cleared outside the unit, or upon debonding or exit from the scheme. The admitted application of this clarification resolved the dispute over inputs used in such manufacture, resulting in quashing of the seizure memoranda and show-cause notice, refund of deposits, and cancellation of the bank guarantee. Interest on the refund remained open for determination in accordance with law.
Duty-free inputs common to finished goods and capital goods may be used for captive manufacture within a 100% Export Oriented Unit where capital goods are accounted for and bonded. Liability arises if those capital goods are cleared outside the unit, or upon debonding or exit from the scheme. The admitted application of this clarification resolved the dispute over inputs used in such manufacture, resulting in quashing of the seizure memoranda and show-cause notice, refund of deposits, and cancellation of the bank guarantee. Interest on the refund remained open for determination in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913