Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
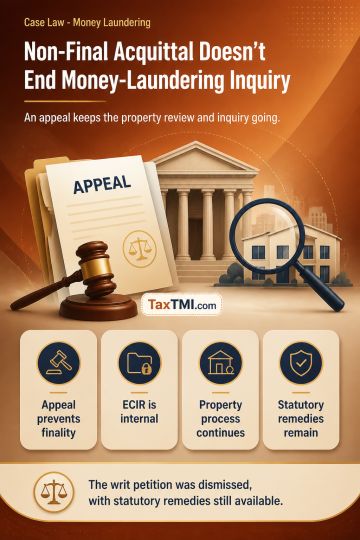
ECIR is an internal, non-statutory departmental record that neither initiates prosecution nor independently imposes penal consequences. A first-instance acquittal in a scheduled offence is not final absolution while subject to appeal and does not determine the legitimacy of separately seized assets. The PMLA's specialised adjudicatory and appellate mechanism governs property retention and confiscation; writ jurisdiction should not bypass it where disputed financial facts require evidentiary assessment. Material indicating contravention of another law must be shared with the relevant agency under section 66(2), independently of an acquittal in a distinct predicate proceeding. The writ petition was dismissed, leaving statutory remedies available.
ECIR is an internal, non-statutory departmental record that neither initiates prosecution nor independently imposes penal consequences. A first-instance acquittal in a scheduled offence is not final absolution while subject to appeal and does not determine the legitimacy of separately seized assets. The PMLA's specialised adjudicatory and appellate mechanism governs property retention and confiscation; writ jurisdiction should not bypass it where disputed financial facts require evidentiary assessment. Material indicating contravention of another law must be shared with the relevant agency under section 66(2), independently of an acquittal in a distinct predicate proceeding. The writ petition was dismissed, leaving statutory remedies available.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915