Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Page of 4918
Press 'Enter' after typing page number.
341 to 360 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
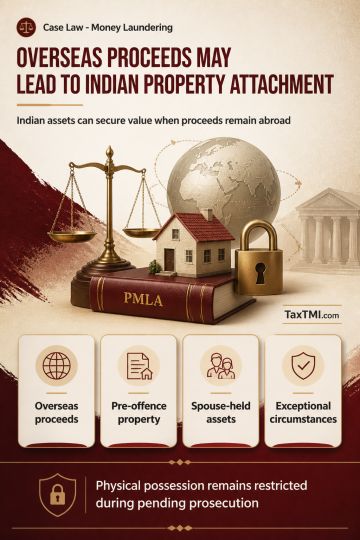
PMLA attachment may extend to Indian property of equivalent value where alleged proceeds of crime remain abroad, including property acquired before the alleged criminal activity or held in a spouse's name if funded by the accused and unsupported by an independent untainted source. Money-laundering is treated as a continuing offence, with timing assessed by reference to laundering acts and attachment; the value-of-proceeds limb independently supports equivalent-value attachment. A provisional attachment order may meet the reasons-to-believe requirement by recording the material, belief and risk of frustrating confiscation, without separate communication. Attachment proceedings do not determine the merits of a pending scheduled offence. Physical possession during pending prosecution is restricted to exceptional circumstances.
PMLA attachment may extend to Indian property of equivalent value where alleged proceeds of crime remain abroad, including property acquired before the alleged criminal activity or held in a spouse's name if funded by the accused and unsupported by an independent untainted source. Money-laundering is treated as a continuing offence, with timing assessed by reference to laundering acts and attachment; the value-of-proceeds limb independently supports equivalent-value attachment. A provisional attachment order may meet the reasons-to-believe requirement by recording the material, belief and risk of frustrating confiscation, without separate communication. Attachment proceedings do not determine the merits of a pending scheduled offence. Physical possession during pending prosecution is restricted to exceptional circumstances.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918