Document Identification Number compliance renders TDS-default orders invalid where mandatory DIN requirements are breached and curative provision does...
Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
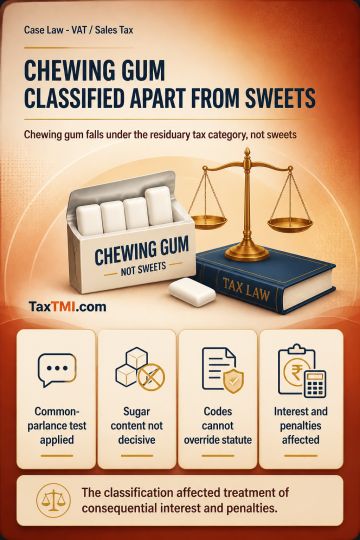
Chewing gum is classified as unclassified goods under residuary Entry 87 of Schedule II to the Gujarat Value Added Tax Act, 2003, rather than as "sweets and sweetmeats" under Entry 74A. Applying the common-parlance test and the Supreme Court position that chewing gum or bubble gum is chewed and discarded rather than eaten, its sugar content does not make it a sweetmeat. Commodity codes used for e-services and prior departmental treatment cannot override statutory classification. As no specific entry covers chewing gum, the residuary entry applies; the contrary classification also affected the treatment of consequential interest and penalties.
Chewing gum is classified as unclassified goods under residuary Entry 87 of Schedule II to the Gujarat Value Added Tax Act, 2003, rather than as "sweets and sweetmeats" under Entry 74A. Applying the common-parlance test and the Supreme Court position that chewing gum or bubble gum is chewed and discarded rather than eaten, its sugar content does not make it a sweetmeat. Commodity codes used for e-services and prior departmental treatment cannot override statutory classification. As no specific entry covers chewing gum, the residuary entry applies; the contrary classification also affected the treatment of consequential interest and penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI