Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
Appellate enhancement is confined to income sources examined in...
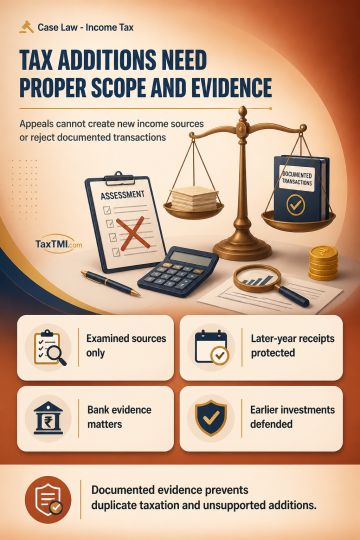
Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additions.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Appellate enhancement is confined to income sources examined in assessment and cannot introduce sale consideration as a new taxable source where only related expenditure was scrutinised. Advance rental receipts already offered in later years are not taxable again absent accrual in the relevant year, preventing double taxation. Recorded bank credits, loans and advances supported by ledgers, confirmations and banking evidence cannot be treated as unexplained without adverse material. Likewise, no unexplained-investment addition arises for shareholdings acquired in earlier years, while documentary proof of disclosed cash sources and individual-to-HUF transfers shifts the evidentiary burden to the Revenue.
Appellate enhancement is confined to income sources examined in assessment and cannot introduce sale consideration as a new taxable source where only related expenditure was scrutinised. Advance rental receipts already offered in later years are not taxable again absent accrual in the relevant year, preventing double taxation. Recorded bank credits, loans and advances supported by ledgers, confirmations and banking evidence cannot be treated as unexplained without adverse material. Likewise, no unexplained-investment addition arises for shareholdings acquired in earlier years, while documentary proof of disclosed cash sources and individual-to-HUF transfers shifts the evidentiary burden to the Revenue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912