Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Page of 4915
Press 'Enter' after typing page number.
161 to 180 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
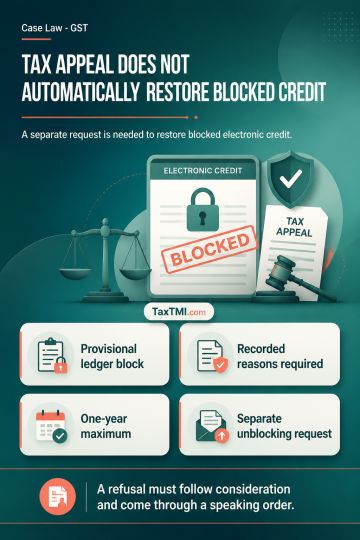
Rule 86A blocking of an electronic credit ledger is a provisional measure that requires recorded reasons and cannot continue beyond one year. Filing an appeal with the prescribed pre-deposit creates a deemed stay of recovery for the remaining demand, preventing appropriation from the electronic cash ledger and the blocked credit ledger. That recovery stay does not automatically lift the separate Rule 86A blocking order. Unblocking must be sought independently, and any refusal should be issued through a speaking order after consideration of the request.
Rule 86A blocking of an electronic credit ledger is a provisional measure that requires recorded reasons and cannot continue beyond one year. Filing an appeal with the prescribed pre-deposit creates a deemed stay of recovery for the remaining demand, preventing appropriation from the electronic cash ledger and the blocked credit ledger. That recovery stay does not automatically lift the separate Rule 86A blocking order. Unblocking must be sought independently, and any refusal should be issued through a speaking order after consideration of the request.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915