Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
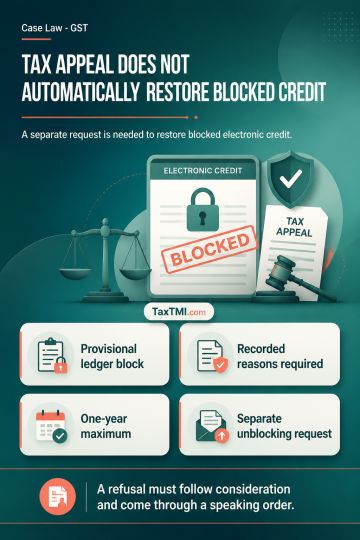
Rule 86A blocking of an electronic credit ledger is a provisional measure that requires recorded reasons and cannot continue beyond one year. Filing an appeal with the prescribed pre-deposit creates a deemed stay of recovery for the remaining demand, preventing appropriation from the electronic cash ledger and the blocked credit ledger. That recovery stay does not automatically lift the separate Rule 86A blocking order. Unblocking must be sought independently, and any refusal should be issued through a speaking order after consideration of the request.
Rule 86A blocking of an electronic credit ledger is a provisional measure that requires recorded reasons and cannot continue beyond one year. Filing an appeal with the prescribed pre-deposit creates a deemed stay of recovery for the remaining demand, preventing appropriation from the electronic cash ledger and the blocked credit ledger. That recovery stay does not automatically lift the separate Rule 86A blocking order. Unblocking must be sought independently, and any refusal should be issued through a speaking order after consideration of the request.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913