Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
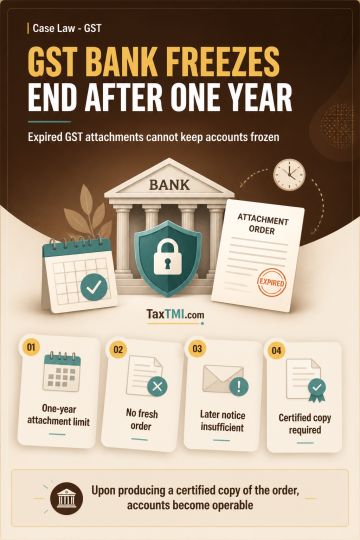
Provisional attachment of bank accounts under GST is a pre-emptive revenue-protection measure that ceases by operation of law one year after the attachment order. Continued freezing cannot rest on an expired attachment where no fresh provisional attachment order has been issued. Where account holders were not recipients of a later demand-cum-show cause notice, that notice did not provide a basis to maintain restrictions on their accounts. The lapsed attachments required the bank accounts to be defreezed and made operable upon production of a certified copy of the order.
Provisional attachment of bank accounts under GST is a pre-emptive revenue-protection measure that ceases by operation of law one year after the attachment order. Continued freezing cannot rest on an expired attachment where no fresh provisional attachment order has been issued. Where account holders were not recipients of a later demand-cum-show cause notice, that notice did not provide a basis to maintain restrictions on their accounts. The lapsed attachments required the bank accounts to be defreezed and made operable upon production of a certified copy of the order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915