Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
    Fraudulent CIRP initiation permits recall, but a mature collective process may continue after stakeholder assessment.
    Mandatory liquidation after CIRP expiry applies despite failed CoC liquidation vote, later expressions of interest, or MSME eligibility claims.
    Further investigation under anti-money-laundering law may continue before charges are framed without prior Criminal Court permission.
    Appellate scrutiny of PMLA bail orders distinguishes invalid grant from cancellation based on subsequent conduct.
    PMLA attachment of mortgaged property turns on the secured creditor's due diligence and links to alleged crime.
    Government grants-in-aid lacking service quid pro quo fall outside service tax; recorded reverse-charge liabilities are time-barred.
    Electronic evidence certification determines whether alleged clandestine removal data can support excise duty quantification and related penalties.
    Third-Party Electronic Records Require Proven Authenticity and Independent Corroboration Before Supporting Clandestine Clearance Demands
    Tariff classification distinguishes batter-coated namkeen from oil-fried salted peanuts, while allowing ISD credit and removing interpretational penal...
    Deemed service of a correctly addressed cheque dishonour demand notice satisfies the statutory requirement despite receipt by a family member.
    Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
    Judicial review of disciplinary complaint closures remains limited to legality, leaving plausible disciplinary findings undisturbed.
    Minimum import price condition for Virgin Multi-layer Paper Board imports remains extended under existing terms.
    RoDTEP Scheme continuation preserves export duty remission eligibility and existing rates, caps, and conditions for eligible exporters.
    Clearing corporation recognition renewed subject to ongoing regulatory conditions throughout the three-year recognition period.
    Special additional excise duty on exported aviation turbine fuel is revised under the amended central excise rate framework.
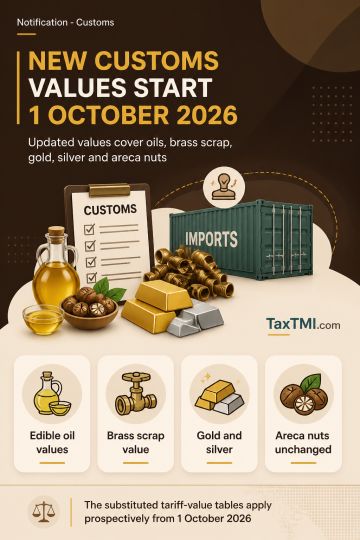
    Customs tariff values for edible oils, brass scrap, gold, silver and areca nuts take effect prospectively.
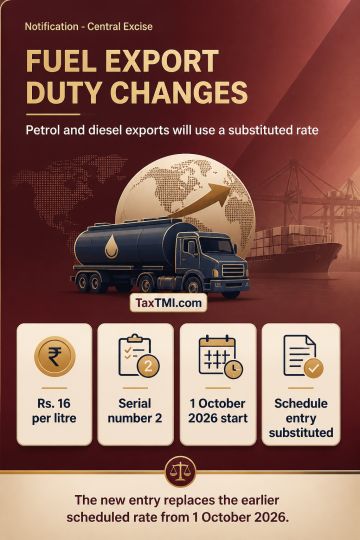
    Special additional excise duty on fuel exports is revised through a substituted rate with prospective effect.
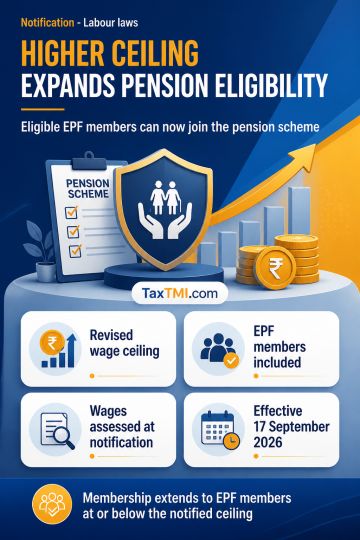
    Revised wage ceiling extends pension scheme membership to eligible provident fund members previously outside the scheme.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Pre-GST service tax paid on advances for flat bookings later...

Pre-GST service tax refunds for cancelled flat bookings must be claimed in cash, not through GST input tax credit.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST September 26, 2026 Case Laws AT
Pre-GST service tax paid on advances for flat bookings later cancelled after the appointed day does not qualify as input tax under the CGST/SGST Acts and cannot be carried as GST input tax credit. Where services are ultimately unprovided, the transitional provision requires the service-tax refund claim to be processed under the existing law and paid in cash. Taxpayers cannot adjust that claim through an electronic credit ledger without specific statutory authority. The claimed GST credit was therefore inadmissible.

Topics

Acts Income Tax