Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
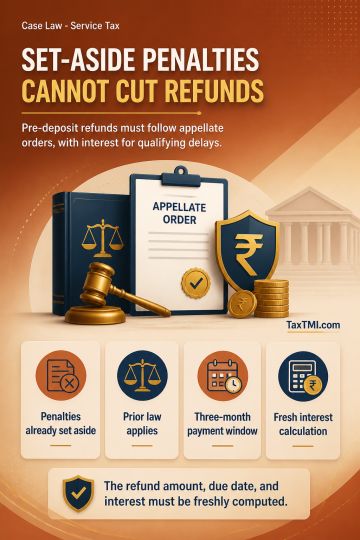
Refunds of pre-deposit arising from appellate relief must be determined under the appellate order; penalties already set aside cannot be recovered by appropriating the refund, and setting aside the Event Management Services demand makes the corresponding deposit refundable. For appeals pending when the statutory amendment took effect, the unamended Section 35FF regime applies. Interest on delayed pre-deposit refund accrues only if payment is not made within three months of the jurisdictional authority receiving the appellate order. The refund amount, due date and consequential interest require fresh computation.
Refunds of pre-deposit arising from appellate relief must be determined under the appellate order; penalties already set aside cannot be recovered by appropriating the refund, and setting aside the Event Management Services demand makes the corresponding deposit refundable. For appeals pending when the statutory amendment took effect, the unamended Section 35FF regime applies. Interest on delayed pre-deposit refund accrues only if payment is not made within three months of the jurisdictional authority receiving the appellate order. The refund amount, due date and consequential interest require fresh computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918