Anti-profiteering obligations survive business demerger, complaint withdrawal, and customized supply arrangements where rate-reduction benefits are no...
Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Page of 4915
Press 'Enter' after typing page number.
121 to 140 of 98300 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
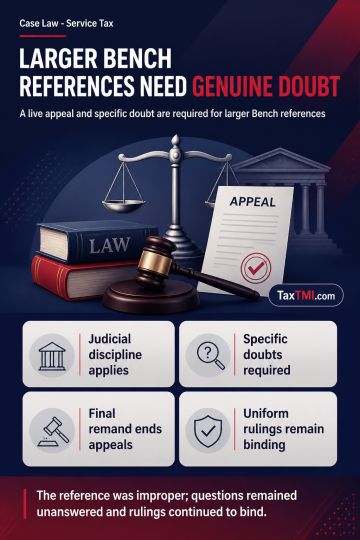
Judicial discipline prevents a lesser-strength Tribunal Bench from differing from or overruling a greater-strength Bench. It may record specific doubts and request the President to constitute a larger Bench; the President's statutory power to constitute Benches is not limited by the strength of the referring or questioned Bench. A reference must identify an overlooked provision, binding precedent, apparent error, or conflicting view. It cannot reopen uniform decisions through broad questions. Where remand had finally disposed of the appeal, no live lis remained and an opinion on refund limitation would have been advisory. The reference was improper, its questions remained unanswered, and uniform Tribunal rulings continued to bind lesser Benches and departmental authorities.
Judicial discipline prevents a lesser-strength Tribunal Bench from differing from or overruling a greater-strength Bench. It may record specific doubts and request the President to constitute a larger Bench; the President's statutory power to constitute Benches is not limited by the strength of the referring or questioned Bench. A reference must identify an overlooked provision, binding precedent, apparent error, or conflicting view. It cannot reopen uniform decisions through broad questions. Where remand had finally disposed of the appeal, no live lis remained and an opinion on refund limitation would have been advisory. The reference was improper, its questions remained unanswered, and uniform Tribunal rulings continued to bind lesser Benches and departmental authorities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915