Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
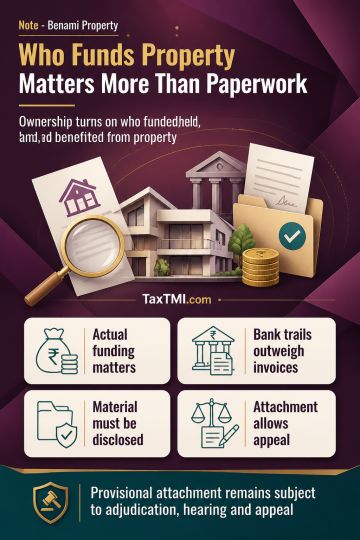
Benami character under Section 2(9)(A) depends on the real relationship between consideration, holding and the direct or indirect benefit of the person providing funds, rather than transaction form. Bank funds and their proceeds may constitute property. A cash-to-bank trail through entities controlled by an alleged benamidar, supported by a sworn statement and surrounding commercial circumstances, may outweigh invoices and ledgers lacking independent substantiation. Procedural fairness requires disclosure of relied-upon material and a meaningful opportunity to respond; denial of cross-examination requires demonstrable prejudice. Provisional attachment remains subject to adjudication, hearing and appeal, while temporal application of amended definitions turns on whether property was transferred or continued to be held after commencement.
Benami character under Section 2(9)(A) depends on the real relationship between consideration, holding and the direct or indirect benefit of the person providing funds, rather than transaction form. Bank funds and their proceeds may constitute property. A cash-to-bank trail through entities controlled by an alleged benamidar, supported by a sworn statement and surrounding commercial circumstances, may outweigh invoices and ledgers lacking independent substantiation. Procedural fairness requires disclosure of relied-upon material and a meaningful opportunity to respond; denial of cross-examination requires demonstrable prejudice. Provisional attachment remains subject to adjudication, hearing and appeal, while temporal application of amended definitions turns on whether property was transferred or continued to be held after commencement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921